NVIDIA Kumo Forecast: Pretrained Representations, Retrieval, Interpretability
NVIDIA Kumo Forecast (formerly NV-Tesseract Forecasting) is a multivariate time-series forecasting model that combines a pretrained Transformer backbone with Domain-Aware Representation and Retrieval (DARR), a context-enhanced mode that blends direct model predictions with patterns retrieved from historical data, plus interpretability for the results. The library exposes a DataFrame-first API, configurable forecast horizons, optional historical context for retrieval, and an interpretability framework that produces horizon-specific explanations without modifying the underlying forecaster. It is available under Apache 2.0, with model code in NVIDIA/Kumo-TS and weights in nvidia/Kumo-Forecast.
The design distinguishes direct forecasting from retrieval-augmented forecasting. In the direct path, a MOMENT-based Transformer and a trained forecasting head predict future values. In DARR mode, the system retrieves related patterns from historical data using a nearest-neighbor approach and combines that information with the direct forecast. There is therefore a distinction between the model’s input window, which supplies the recent observations used for the forecast, and a separate historical DataFrame that can act as retrieval context. The library exposes this through a context_df argument, and configuration options control how strongly the final prediction relies on each pathway. The DARR approach is described in the paper Memory-Augmented Forecasting: Scalability and Generalization Across Temporal Domains.
Kumo-Forecast has four main components: a pretrained temporal encoder, a trainable forecasting head, historical-pattern retrieval, and an interpretability framework. The encoder is the MOMENT-1-large Transformer backbone, an approximately 340-million-parameter base encoder, with encoder and embedder weights kept frozen while the forecasting head is trained. That separates pretrained representation learning from the task-specific prediction layer. The forecasting head maps representations to future values for the requested horizon; for horizons beyond the model’s native capability, autoregressive extension is supported, distinguishing a directly generated forecast from one extended recursively.
DARR augments direct forecasting with k-nearest-neighbor retrieval from historical context data. The SDK takes historical context through a separate context_df argument, so callers can supply a DataFrame of past observations with dimensions similar to the input context when using that mode.
The interpretability framework is model agnostic. When enabled, it returns an explanation bundle containing lag and feature attributions per forecast horizon, semantic-flow diagnostics, trajectory-stability diagnostics, and optional embedding Integrated Gradients. These outputs accompany the forecast rather than requiring a different forecasting architecture. More detail is in the paper NVExplain: Explaining Time Series Forecasting with Latent Trajectory Analysis and Structure-Preserving Surrogates.
The stated limitations are that data must be numeric, temporal data; supported input sequence lengths are 256, 512, 1024, and 2048 observations; inputs consist of a timestamp column and one or more numeric value columns, represented as pandas DataFrame or CSV/JSON input. In DARR mode, the context dimensions must be similar to the input context. For application-specific evaluation, NVIDIA recommends comparing the direct and retrieval-enhanced configurations on the same held-out forecasting windows and validating forecast quality across intended horizons and operating conditions. The Kumo-TS repository also provides an example for fine-tuning Kumo-Forecast on a user-supplied CSV, giving both a pretrained inference workflow and a starting point for adaptation.
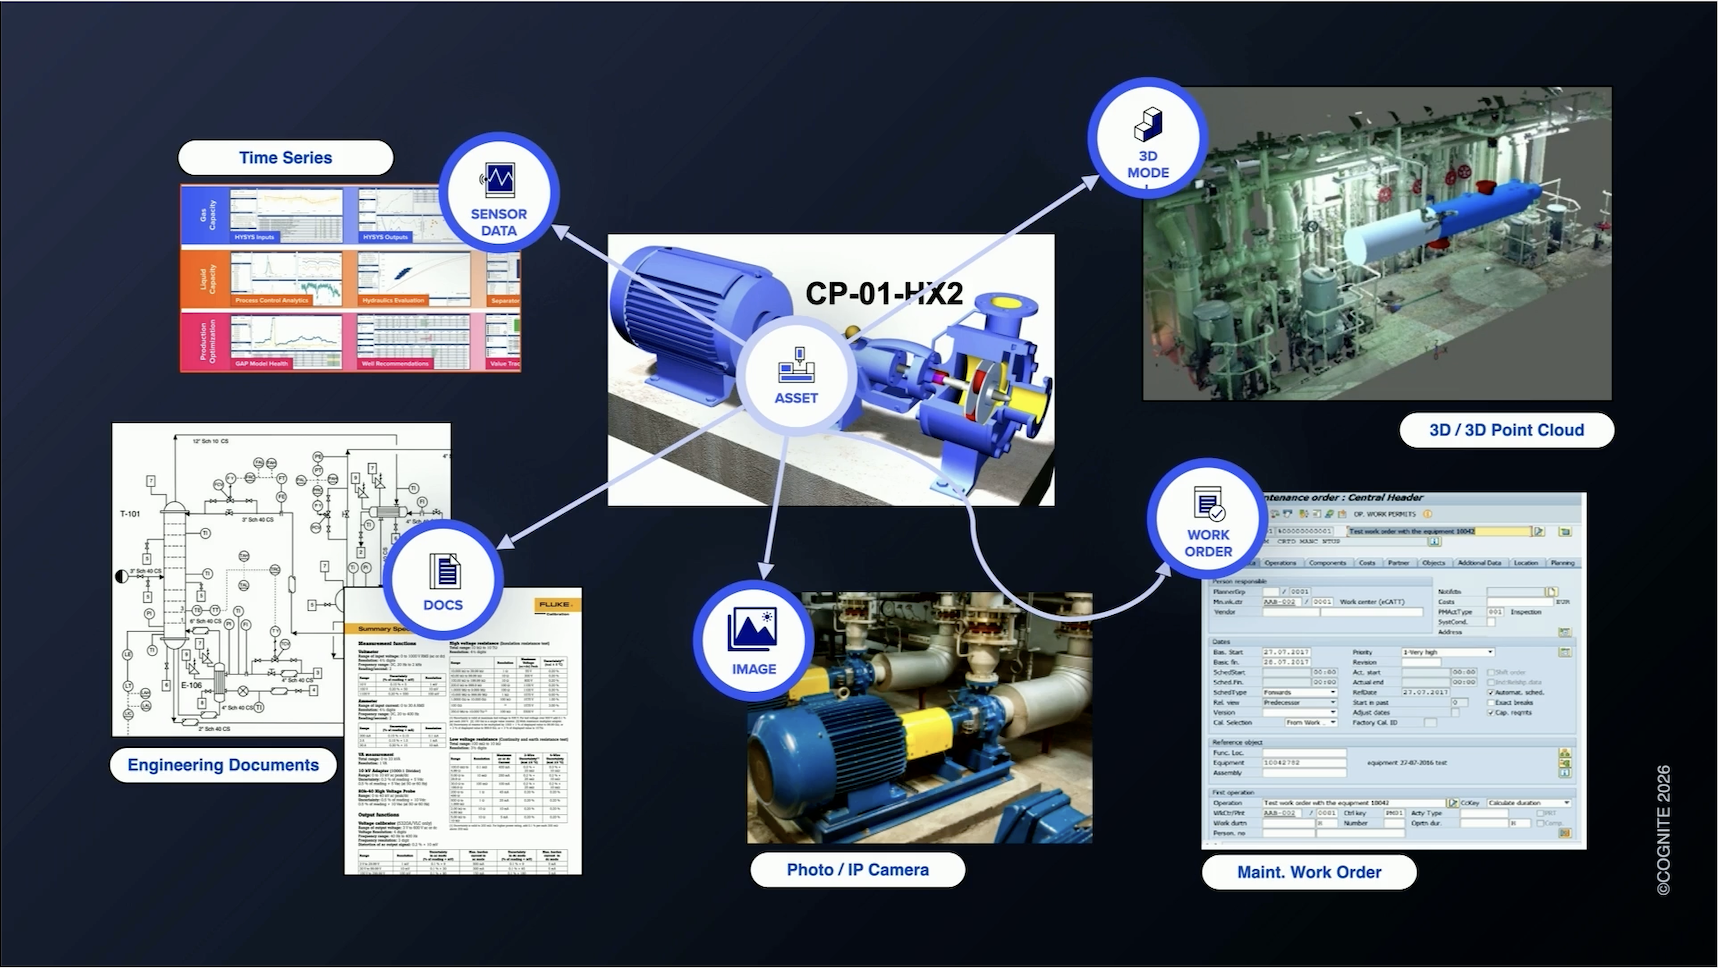
The Factory Operations (FOX) Blueprint includes Early Access to a Predictive Maintenance module that uses Kumo Anomaly and Kumo Forecast to analyze real-time data and predict future anomalies. A platform integration demo is available from GTC San Jose 2026.